Ottawa Mortgage Blog
Your Trusted Ottawa Mortgage Experts
The Cash Dam Strategy: How Canadian Rental Property Owners Can Make Mortgage Interest Tax Deductible
November 10, 2026 | Posted by: Jamie Small - Ottawa Mortgage Broker
If you own a rental property or are considering buying one, a strategy could supercharge your return on investment by making your home mortgage tax-deductible.The traditional way to run a rental property is for rent to come in and go right back out to cover the rental's mortgage, taxes, insurance, maintenance, and other expenses. Meanwhile, the mortgage on your own home sits there, costing you interest you can never write off.
What if that same rent could quietly turn your home mortgage into tax-deductible debt? That's the idea behind a strategy called the cash dam. It can put thousands of dollars back in your pocket at tax time, shave years off your mortgage, and create an opportunity for significant wealth improvement.
Why your home mortgage isn't tax-deductible (yet)
In Canada, you can't deduct mortgage interest on your principal residence. Unlike in the U.S., you can't write off mortgage interest just for owning a home.The reason comes down to the loan's purpose. Interest is generally deductible only when you borrow money to earn income. Your home doesn't produce income, so its mortgage interest doesn't qualify.
A rental property, on the other hand, does produce income. And that's where the opportunity lies. The cash dam is a variation of the well-known Smith Manoeuvre, designed specifically for rental property owners.
How the Cash Dam Works
The cash dam changes where your rent goes, not how much you earn. Imagine a dam redirecting a river's flow.The Traditional Way: rent comes in, and you use it to pay the rental property's expenses, such as mortgage payments, property taxes, insurance, maintenance and utilities.
The Cash Dam Way: it starts with a re-advanceable mortgage on your home, which combines your mortgage with a home equity line of credit (HELOC) that grows as you pay down the mortgage. Then:
- Rent goes to your home mortgage. Each month, your rental income is applied as a lump-sum prepayment on your principal residence mortgage.
- The HELOC covers the rental's expenses. You borrow from the HELOC to pay the rental property's expenses.
- The debt changes character. Because the HELOC funds cover expenses on an income-producing property, the interest becomes tax-deductible.
A simple example
Say your rental brings in $2,000 per month, or $24,000 per year. Under a cash dam, that $24,000 goes against your home mortgage each year, and you re-borrow the same amount on the HELOC to run the rental.Assuming a 5% interest rate and a 40% marginal tax rate, here's how the deductible debt and the resulting tax refund can build:
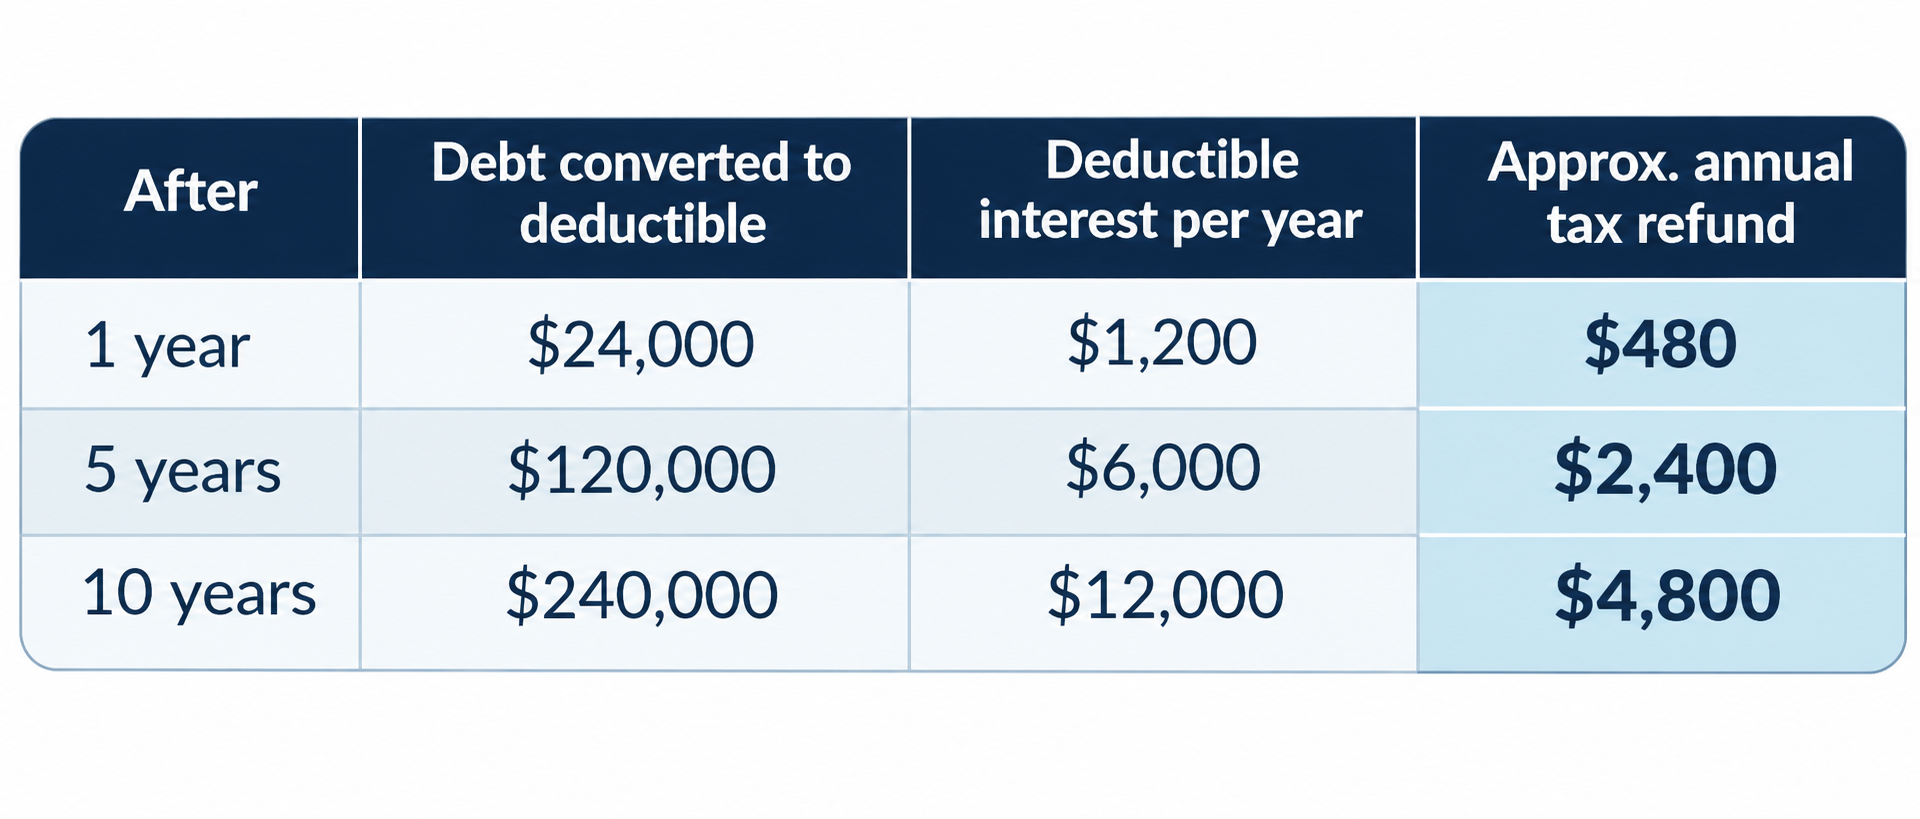
The refund keeps growing as more debt converts. Add those refunds up over the life of the strategy, and the total often reaches tens of thousands of dollars.
This example is simplified for illustration. Actual results depend on your rent, expenses, interest rates, tax bracket and how the strategy is set up.
Three Big Benefits to the Cash Dam
The Cash Dam can be a powerful strategy with multiple financial benefits.1. Tax refunds that grow every year
As more of your debt becomes deductible, your annual tax refund gets bigger. That's real cash back in your pocket, and over the full strategy, it often adds up to tens of thousands of dollars.2. Years off your mortgage
Put those refunds toward your home mortgage to pay it off even faster. Many homeowners shave years off their amortization, saving tens or even hundreds of thousands of dollars in mortgage payments.3. A real boost to your net worth
Once you pay off your home mortgage early, you free up the money you were putting toward it every month. Invest those payments for the years you would otherwise still be paying the bank, and your wealth can grow significantly.Is a Cash Dam Right for You?
The cash dam may be a good fit if you:• Own a rental property, or are planning to buy one
• Have a mortgage on your principal residence
• Have enough home equity to qualify for a re-advanceable mortgage (Typically 20% equity)
Because every situation is different, we always recommend reviewing the strategy with your accountant or tax advisor before you start.
How our Team Helps
We don't just explain the cash dam. We map it out for your situation and help you put it in place, start to finish.We run your numbers. Using an advanced calculator, we show you the exact benefits of the strategy for you, including:
• How much you could receive in tax refunds
• How long it would take to convert all your debt to tax-deductible debt
• How much sooner your home mortgage could be paid off, and how many payments you'd save
• How the strategy would increase your overall net wealth
We set it up properly. We arrange the right financing and help build the plan itself, structured to follow CRA rules from day one.
We connect you with the right people. Need an accountant or a lawyer who understands this strategy? We can introduce you to trusted professionals.
Find Out What a Cash Dam Could Do for You
The only way to know your numbers is to run them. Our team has the expertise and the tools to assess your situation, show you exactly what the benefits could be, and explain it all in plain language.If you own a rental property and have a mortgage on your home, book your free, no-obligation cash dam assessment today. It could be a game changer for your finances.
Book your free assessment · Call 613-797-1929 · Email jamie@themortgageadvisors.com
This article is for general information only and isn't tax, legal or financial advice. Speak with a qualified tax professional about your specific situation before implementing any tax strategy.